
Does Your US Subsidiary Need an Audit for the APR? The Control Test and Which Report Counts

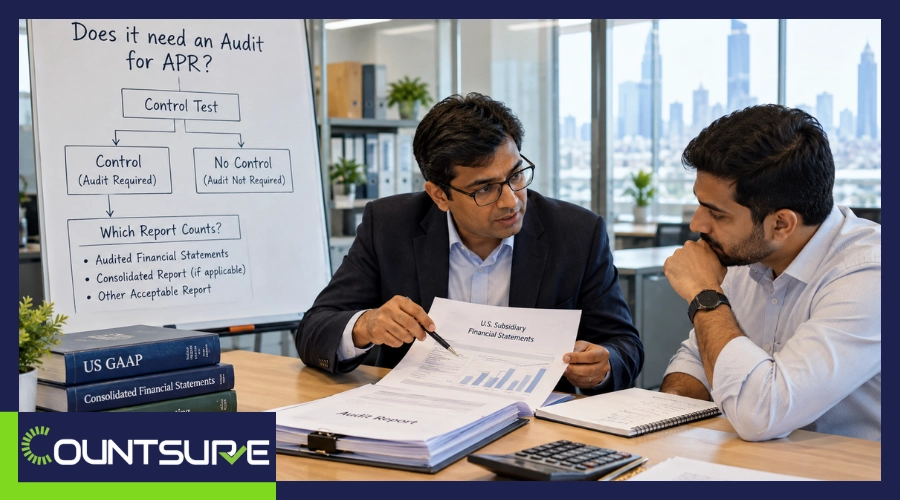
The short answer: An audit for the APR is mandatory when the Indian investor controls the foreign company. Unaudited statements, certified by the Indian investor’s statutory auditor, are allowed only when there is no control and the host country does not require an audit. Control includes the right to appoint a majority of the board, or 10% or more of the voting rights through shares or agreements. So a wholly owned or majority-owned US subsidiary needs audited statements every year, and a review or compilation does not count.
Whether an audit for the APR is mandatory is the first question most Indian parents ask about their US subsidiary. The APR, or Annual Performance Report, is the yearly report filed through your authorized dealer bank (your AD bank) on each overseas company you have invested in. The answer turns on one word: control.
The difficulty is that “control” is wider than most people expect. In our APR audits for US subsidiaries of Indian companies, we regularly meet minority investors who assumed they were exempt, and wholly owned subsidiaries filing on review reports their banks later rejected.
This guide explains the control test in plain terms, works through five common ownership structures, and shows which report your AD bank will actually accept.
Key Takeaways
- An audit for the APR is mandatory whenever the Indian investor controls the foreign company.
- Control includes a board majority, control of management or policy decisions, or 10% or more of voting rights through shares or agreements.
- Unaudited statements are allowed only when there is no control and the host country does not mandate an audit.
- US law does not generally require a private company audit, so for a US subsidiary the control test alone decides.
- A stake under 10%, held without control and with no other financial commitment, needs no APR at all.
- A review or compilation is not an audit, so neither meets the audited statements rule.
When Is an Audit for the APR Mandatory?
An audit for the APR is mandatory whenever the Indian investor has control of the foreign company. Under Regulation 10(4) of India’s Overseas Investment Regulations, 2022, the APR is based on the foreign company’s audited financial statements. That is the default for every filer.
There is one exception, and it needs both of these to be true:
- No control. The Indian investor does not control the foreign company.
- No host-country audit requirement. The laws of the country where the company sits do not require its accounts to be audited.
When both hold, the APR can use unaudited statements. They must be certified by the Indian investor’s statutory auditor, or by a chartered accountant (CA) where the investor has no statutory audit, such as an individual. If either condition fails, the audit is required.
What Counts as "Control" for ODI?
Control for overseas direct investment (ODI) means the right to appoint a majority of the directors, or to control management or policy decisions. India’s Overseas Investment Rules, 2022 define it broadly. Control can come from shareholding, management rights, shareholders’ agreements or voting agreements, held alone or together with others, directly or indirectly.
A board majority
If you can appoint more than half the board, you have control. A wholly owned subsidiary meets this by definition, and so does a joint venture where your shareholders’ agreement gives you most of the board seats.
10% or more of the voting rights
The definition also covers shareholding or agreements that give you 10% or more of the voting rights. This is the part that catches minority investors. A 15% or 25% stake that looks passive can still count as control.
Practitioners read this clause in different ways for stakes between 10% and 50% that carry no board rights. The safe course is to treat that band as control, and therefore as needing an audit, unless your AD bank confirms in writing that it accepts unaudited statements.
Control through agreements, not just shares
Control does not need a large shareholding. A voting agreement that pools your votes with another holder’s, a veto over the budget, or a right to appoint the CEO can all give control. Read your shareholders’ agreement, not only your cap table (the company’s list of owners and their stakes).
Does the US Require an Audit Anyway?
No. US law does not generally require a privately held company to have its financial statements audited. A US subsidiary may still need one for a lender, an investor or a government contract, but nothing in federal law imposes it on a private company by default.
That matters because it removes one of the two conditions in the exception. For a US subsidiary, the host-country condition is usually met, so the control test alone decides. Control means an audit. No control means certified unaudited statements are allowed.
Not sure whether your stake counts as control?
Send us your cap table and shareholders’ agreement. We will tell you whether your US company needs an audit for its APR, and quote a fixed fee for each year before any work starts.
Five Scenarios: Audit, Unaudited, or No APR at All
The quickest way to apply the rules is to test your structure against common cases. Each row below assumes a US company and an Indian investor, which may be a company, an LLP or an individual.
| Indian investor's position | Control? | What the APR needs |
|---|---|---|
| 100% owner (wholly owned subsidiary) | Yes | Audited statements |
| 51% joint venture with a board majority | Yes | Audited statements |
| 15% stake with a voting agreement and a board seat | Treat as yes | Audited statements |
| 8% stake plus a loan to the company, no control | No | Unaudited statements, certified |
| 8% stake, equity only, no control | No | No APR required |
The last two rows look alike but end differently. An APR is not required at all for a stake under 10% held without control, as long as there is no other financial commitment. Once the investor also lends money or gives a guarantee, an APR is due, though it can use certified unaudited statements.
Worked example: when 15% of the shares is 25% of the votes
Equity percentage and voting percentage are not always the same, and the control test looks at votes. Consider a Pune-based software company that invests in a California startup alongside US founders.
The startup has 10,000 shares. Of these, 4,000 are non-voting preferred shares held by an angel investor, leaving 6,000 voting shares. The Indian company holds 1,500 voting shares.
| Measure | Calculation | Result |
|---|---|---|
| Share of total equity | 1,500 / 10,000 | 15% |
| Share of voting rights | 1,500 / 6,000 | 25% |
| With a voting agreement over 600 more votes | 2,100 / 6,000 | 35% |
On equity alone, the stake reads as 15%. On votes, it is 25%, and 35% once the voting agreement is counted. Both figures are well above the 10% voting line, and the company also holds one of five board seats. It should treat the startup as controlled and get an audit for each APR.
Does one of these scenarios match your structure, or sit somewhere in between?
Book a 30-minute call with a US CPA. We will walk through your shareholding, voting rights and any loans to the US company, and tell you whether you need audited statements, certified unaudited statements or no APR at all.
Audit, Review or Compilation: Which Report Does the RBI Accept?
For a controlled US subsidiary, only a full audit meets the rule. US CPA firms offer three levels of service on financial statements, and the names are easy to confuse. The table shows how they differ:
| Report | What the CPA does | Meets the APR audit rule? |
|---|---|---|
| Audit | Tests the records and gives an opinion (reasonable assurance) | Yes |
| Review | Asks questions and runs analysis, no opinion (limited assurance) | No |
| Compilation | Presents management's numbers, no assurance | No |
A review, prepared under the AICPA’s Statements on Standards for Accounting and Review Services (SSARS), costs less than an audit. That is why it is often offered as a shortcut. But a review report states that it is not an audit, so it cannot support an APR that must rest on audited statements. Our guide to what an APR audit involves explains what the full audit covers.
A review can still be useful where unaudited statements are allowed. In that no-control case, a review gives your CA more comfort before certifying the figures, though it is not required.
How Do You Run the Control Test on Your Own Structure?
You run the control test by checking four documents against the definition, in order. Most investors can settle the question in an afternoon. Where the answer stays unclear, put the facts to your AD bank in writing before the APR season starts.
- Pull the cap table. List every share class and mark which ones carry votes. Work out your percentage of the voting shares, not of total equity.
- Read the shareholders’ agreement. Note any right to appoint directors, veto budgets or key hires, or appoint the CEO. Any of these can create control on its own.
- Look for voting agreements. Add any votes you control through pooling or proxy arrangements to your own. The total is what the 10% line is measured against.
- List every financial commitment. Include loans, guarantees and any other money owed by the US company. These decide whether a small, passive stake needs an APR at all.
Write the result down once, with the documents attached, and keep it in your APR file. Your CA and AD bank will ask the same question every year, and a short note that answers it saves weeks of back and forth.
What changes the answer from one year to the next?
Control is tested each year, so a change in your stake can change what the APR needs. A new funding round can dilute you below 10% of the votes. A new shareholders’ agreement can hand you a board seat. A loan from the parent can turn a no-APR stake into one that must file.
Review the test whenever the cap table or the agreements change, not only at year-end. Catching the change early gives you time to book an audit before the December rush, rather than discovering in November that one is needed.
What If Past APRs Were Filed on Unaudited Statements?
If a controlled subsidiary’s past APRs were filed on unaudited or reviewed statements, they did not meet the rule. The usual fix is to audit those years and refile, working with your CA and AD bank. Any APR that was never filed can still be regularized for up to three years from its due date with a fee of Rs 7,500 per report, as our guide to the APR late submission fee explains.
Going forward, plan the audit into the calendar so it is signed well before December 31. Our month-by-month APR due date timeline shows when each step should start, and our APR filing service takes the audited figures through to your bank’s acknowledgement.
Audit for APR FAQs
1. Is an audit mandatory for the APR?
Yes, when the Indian investor controls the foreign company. Unaudited statements are allowed only when there is no control and the host country does not require an audit.
2. Does owning 10% of a US company mean control?
It can. Control includes 10% or more of the voting rights through shares or agreements. Check your voting percentage, not just your equity percentage, and treat stakes from 10% to 50% as control unless your AD bank confirms otherwise.
3. Can a review report be used for the APR?
Not for a controlled subsidiary. A review gives limited assurance and no opinion, so it does not produce audited financial statements.
4. Does a dormant US subsidiary need an audit for the APR?
Yes, if you control it. Inactivity is not an exemption, though a dormant company’s audit is usually short and simple.
5. Who certifies unaudited statements for the APR?
The Indian investor’s statutory auditor certifies them. Where the investor has no statutory audit, such as an individual, a practicing chartered accountant certifies them.
6. Is an APR needed for a stake under 10%?
Not if the stake is held without control and there is no other financial commitment, such as a loan or guarantee. Add a loan, and an APR becomes due.
7. Does a US LLC owned by an Indian company need an audit for the APR?
Yes, if the Indian company controls it, which a single-member LLC almost always is. Its US tax filing does not replace audited statements.
8. Can an audit done for a US lender be used for the APR?
Usually, yes. If it is a full audit of the same year’s financial statements by a US CPA firm, the same report can support the APR. Check that the year-end matches the year being reported.
Conclusion: Is an Audit for APR Mandatory for Your US Subsidiary?
An audit for the APR is mandatory whenever your Indian company controls the US subsidiary. Because US law does not generally require private company audits, control is the only test that matters. A board majority, control of management, or 10% or more of the voting rights all count. Wholly owned and majority-owned subsidiaries need audited statements every year, and a review or compilation will not pass. Only a truly passive minority stake escapes the audit.
- Check your voting percentage, not only your share of equity.
- Read your shareholders’ agreement for board, veto and voting rights.
- Treat 10% to 50% stakes as control unless your AD bank confirms otherwise.
- Replace any review-based APR with a full audit for each affected year.
Settle the control question once, and every APR after it gets simpler.
Ready to get this year's APR audit booked?
Tell us about your US subsidiary, its year-end and your stake. We will confirm what your APR needs and send a fixed-fee proposal with the report date and the records list.
Parth Shah, Managing Director
(CPA-US, FCA, RV-S&FA, DISA)
Parth Shah who is head of Accounts and Book keeping has experience of more than 10 years. A Certified Public Accountant – US, fellow Chartered Accountant, Registered Valuer and Diploma in Information System Audit.