
What Is an APR Audit? A Plain Guide for Indian Companies With a US Subsidiary
 Parth ShahPublished:4 days ago
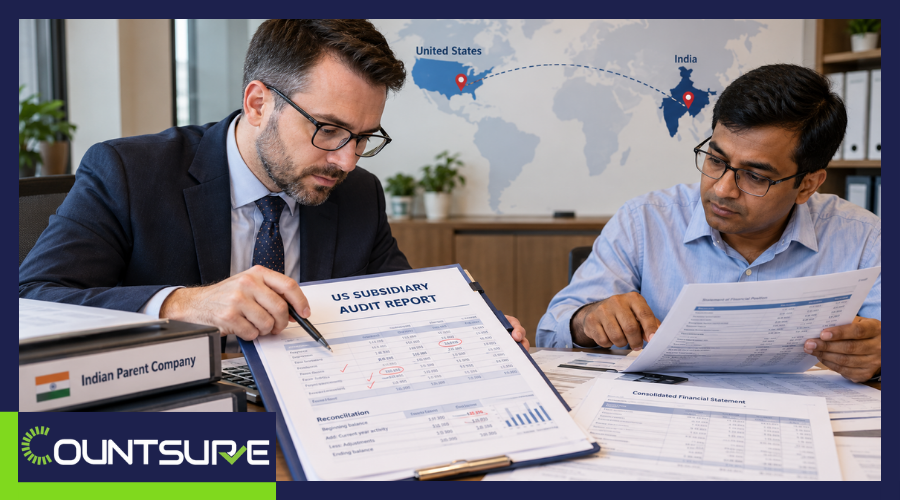
The short answer: An APR audit is an independent audit of your US subsidiary’s annual financial statements, done so the Indian parent can file its Annual Performance Report (APR) with the RBI. Where the Indian company controls the US subsidiary, the APR must be based on audited statements. The APR is due by December 31 each year. For a US subsidiary, the audit is performed by a licensed US CPA firm under AICPA auditing standards, and the signed report is what your AD bank and Indian auditor rely on.
If your Indian company owns a US subsidiary, someone has probably told you that you need an “APR audit.” The term sounds like a special kind of audit. It isn’t. An APR audit is an ordinary financial statement audit of the US company, done for one specific purpose: the yearly report your company files on its overseas investment.
That report goes through your authorized dealer bank (your AD bank, the Indian bank that handles your foreign remittances). In our APR audit work for US subsidiaries of Indian companies, the most common confusion is not whether an audit is needed. It is what the audit actually involves, and why a US tax return cannot take its place.
This guide explains it in plain terms: what an APR audit is, what it checks, what the report says, and how the process runs.
Key Takeaways
- An APR audit is an independent audit of a foreign subsidiary’s financial statements that supports the Indian parent’s Annual Performance Report.
- It is needed where the Indian investor controls the foreign company, which covers most wholly owned and majority-owned US subsidiaries.
- For a US subsidiary, the audit follows AICPA auditing standards (GAAS) and is signed by a licensed US CPA firm.
- A review or compilation is not an audit, so neither meets the audited statements rule for a controlled subsidiary.
- A US tax return, including a pro forma Form 1120 with Form 5472, does not replace audited financial statements.
- Once records are complete, fieldwork for one year usually takes 8 to 10 working days.
What Is an APR Audit?
An APR audit is the audit of a foreign subsidiary’s financial statements that the Indian parent uses to file its APR. The auditor examines the subsidiary’s balance sheet, income statement and supporting records, then gives an opinion on whether they are fairly presented. That signed opinion turns the US company’s numbers into “audited financial statements.”
What does "APR" mean?
APR stands for Annual Performance Report. It is a yearly report an Indian investor files on each overseas company in which it has made a direct investment and holds control. The APR summarizes the foreign company’s capital, profit or loss, loans, dividends and net worth for its latest completed financial year. It is filed through the AD bank by December 31 each year.
Why is it called an APR audit if it is a normal audit?
It is called an APR audit because of why it is done, not how. The audit itself is a standard financial statement audit of the US company. The label simply tells everyone the purpose: producing audited figures the Indian parent can report in its APR. The same audit can also serve your Indian auditor when they consolidate the subsidiary into group accounts.
Who Needs an APR Audit?
An Indian company needs an APR audit when it controls its US subsidiary. Under Regulation 10(4) of India’s Overseas Investment Regulations, 2022, the APR is based on the foreign company’s audited financial statements. Unaudited statements are allowed only when the investor has no control and the host country does not require an audit.
Control generally means the right to appoint a majority of the board or to direct management and policy decisions. A wholly owned or majority-owned US subsidiary almost always meets that test. A small passive stake usually does not.
Two situations surprise people. A dormant US company still needs an audit if you control it, because inactivity is not an exemption. A single-member LLC also needs one, even though it may file no separate federal income tax return of its own.
Not sure whether your US subsidiary needs an audit for its APR?
We check your ownership and control position, confirm whether an audit is required, and quote a fixed fee for each year before any work starts. Audits are performed by a US CPA firm under AICPA standards, with reports your AD bank can rely on.
What Does an APR Audit Actually Check?
An APR audit checks that the US subsidiary’s financial statements are free of material misstatement, meaning errors large enough to change a reader’s view. In practice, the auditor spends most of the time on the cross-border items the APR reports. These are the areas where Indian and US books most often disagree.
The money sent from India
The auditor traces every remittance from the Indian parent to the US company’s bank account and its books. Each one must be recorded as either equity or a loan, matching how the Indian side reported it. For an LLC, equity sits in a member’s capital account rather than share capital, which needs careful presentation.
Loans between the two companies
Intercompany loans are confirmed on both sides: principal, interest and the balance at year-end. Interest accrued in the US books must agree with what the Indian parent recorded as income. Any difference has to be explained before the audit can be signed.
Profits and dividends
The auditor checks the profit or loss for the year and any dividends or distributions paid to the Indian parent. These feed straight into the APR’s profit and repatriation figures, so they must agree with bank records on both sides.
Companies your US subsidiary owns
If the US subsidiary owns other companies, called step-down subsidiaries, those holdings must be identified and reported. The auditor confirms the investment balances and whether those companies need their own figures for the APR.
What Does an APR Audit Report Contain?
An APR audit report is a standard independent auditor’s report, issued with the audited financial statements and notes. For a US private company, the report follows the format in AICPA auditing standards (AU-C Section 700). It is addressed to the board or owners and signed in the name of the audit firm.
The report has these main parts, in this order:
- Opinion: names the statements audited and says whether they are fairly presented under US GAAP (generally accepted accounting principles).
- Basis for opinion: confirms the audit followed US auditing standards (GAAS) and that the auditor is independent.
- Management’s responsibilities: preparing the statements and keeping proper controls.
- Auditor’s responsibilities: obtaining reasonable assurance and reporting what was found.
- Signature, city and state, and date: the firm’s name, its location and the report date.
Why AD banks look for a clean opinion
A clean opinion, formally called an unmodified opinion, means the auditor found the statements fairly presented in all material respects. AD banks prefer it because it lets them accept the APR figures without further questions. A qualified opinion, or one with an unresolved limitation, usually leads to queries and delays.
Banks also check that the report comes from a firm licensed in the host country. For a US subsidiary, that means a US CPA firm. Our US GAAP financial statement preparation team can draft the statements before the audit, so they arrive in the right format.
Audit, Review, Compilation or CA Certificate: Which One Counts for the APR?
Only a full audit counts for the APR of a controlled US subsidiary. A review or compilation is a lower level of service, and a certificate from an Indian chartered accountant (CA) on unaudited statements is allowed only in the no-control case. The table shows how they differ:
| Report | Level of assurance | Accepted for a controlled US subsidiary? |
|---|---|---|
| Audit | Reasonable assurance, with an opinion | Yes |
| Review | Limited assurance, no opinion | No |
| Compilation | No assurance | No |
| CA certificate on unaudited statements | Certification only | No, only where there is no control |
A review costs less, which is why it is often suggested. But it does not produce audited financial statements, so an APR filed on a review report fails the rule it is meant to meet.
Is a US Tax Return Enough for the APR?
No. A US tax return is not a substitute for audited financial statements. Tax returns report taxable income under IRS rules, while the APR needs a full balance sheet, net worth and investment figures verified by an auditor.
The gap is widest for single-member LLCs owned by a foreign company. These file a pro forma Form 1120 with Form 5472 to report related-party transactions, as our guide on the Form 5472 and pro forma Form 1120 connection explains. That filing lists transactions but carries no audited balance sheet.
| Factor | US tax return | Audited statements |
|---|---|---|
| Purpose | Report taxable income to the IRS | Present financial position fairly |
| Rules followed | Internal Revenue Code | US GAAP and GAAS |
| Independent opinion | No | Yes |
| Accepted for a controlled APR | No | Yes |
A Worked Example: How an APR Audit Catches a Mismatch
The most common issue an APR audit finds is money recorded one way in India and another way in the US. The example below shows how that plays out and why it matters for the APR.
The situation
A Surat-based diamond trader owns 100% of a New York LLC that sells its stones to US jewelers. During calendar 2025, the Indian company sent the LLC $500,000. In India, it reported the full amount as equity. In the US books, the LLC recorded $300,000 as member’s capital and $200,000 as a loan from the parent.
The arithmetic
The LLC lost $120,000 in 2025. Its net worth depends on how the $500,000 is classified:
| Item | US books as recorded | If all $500,000 is equity |
|---|---|---|
| Member's capital | $300,000 | $500,000 |
| Less: 2025 loss | ($120,000) | ($120,000) |
| Net worth | $180,000 | $380,000 |
| Loan from parent | $200,000 | None |
The two versions show a $200,000 difference in net worth: $380,000 minus $180,000. The APR reports both the equity invested and the net worth, so the Indian figures would not match the US company’s own books.
How the audit resolves it
The auditor asks for the board approvals, bank advices and any loan agreement behind the $200,000. If the documents support a loan, the Indian side must correct its reporting. If they support equity, the US books are adjusted before the audit is signed. Either way, the APR is filed on one consistent set of numbers.
Left unfixed, this kind of mismatch is exactly what an AD bank queries in December. It is far cheaper to resolve during the audit than after the APR is rejected.
Do your US and Indian books show the same numbers for your subsidiary?
Book a 30-minute call with a US CPA. We will look at how your remittances, loans and dividends are recorded on both sides, and flag any mismatch that could hold up your audit or your APR.
How Does an APR Audit Work, Step by Step?
An APR audit runs in six stages, from agreeing the scope to handing over the signed report. Once the US subsidiary’s records are complete, fieldwork for one year usually takes 8 to 10 working days.
- Scoping and engagement letter. The firm confirms the year, the entity and the report date, working back from the December 31 APR deadline.
- Records request. Bank statements, the general ledger, remittance advices, loan agreements and board approvals are collected.
- Intercompany confirmation. Balances with the Indian parent are confirmed on both sides before testing starts.
- The auditor tests balances and transactions and raises any adjustments.
- Draft statements and review. Management approves the final statements and signs a representation letter.
- Signed report. The firm issues the audit report, which goes to your CA for the APR.
Timing matters as much as the steps. Our month-by-month APR due date timeline shows when each stage should start. After the audit, the APR filing process with your AD bank takes the audited figures through to the bank’s acknowledgement.
APR Audit FAQs
1. What is an APR audit?
An APR audit is an independent audit of a foreign subsidiary’s financial statements, used by the Indian parent to file its Annual Performance Report. For a US subsidiary, it is done by a US CPA firm under AICPA standards.
2. Is an audit mandatory for the APR?
Yes, when the Indian investor controls the foreign company. Unaudited statements are allowed only when there is no control and the host country does not require an audit.
3. Who can perform an APR audit for a US subsidiary?
AD banks generally expect a firm licensed in the host country. For a US subsidiary, that is a US CPA firm auditing under US generally accepted auditing standards.
4. Which accounting standards are used for an APR audit?
The US subsidiary’s statements are normally prepared under US GAAP and audited under GAAS. Your Indian auditor then converts the figures for the APR and for group accounts.
5. How long does an APR audit take?
Fieldwork usually takes 8 to 10 working days per year once records are complete. Collecting records and confirming intercompany balances add time, so plan for several weeks overall.
6. Can last year's audit be reused for this year's APR?
No. Each APR covers the latest completed financial year, so each year needs its own audit of that year’s statements.
7. What if the APR audit is not ready by December 31?
8. Does a single-member US LLC need an APR audit?
Yes, if the Indian parent controls it. A single-member LLC may file only a pro forma Form 1120 and Form 5472 with the IRS, but the APR still needs audited statements.
Conclusion: The APR Audit in Plain Terms
An APR audit is a standard audit of your US subsidiary’s financial statements, done so your Indian company can file its Annual Performance Report on audited figures. If you control the US company, it is required every year, whether the company is active, dormant or a single-member LLC. A review, a compilation or a tax return cannot stand in for it. Most of the audit’s value lies in catching mismatches between your Indian and US books before your AD bank does.
- Confirm your control position before assuming an audit is optional.
- Agree remittances and loans with the Indian parent before fieldwork starts.
- Use a US CPA firm so the report meets your AD bank’s expectations.
- Book the audit early so the APR is filed well before December 31.
Get the audit right, and the APR becomes a simple filing.
Ready to get this year's APR audit scheduled?
Tell us about your US subsidiary and its year-end. We will send a fixed-fee proposal with the report date, the records we need and the steps to get your APR filed on time.
Parth Shah, Managing Director
(CPA-US, FCA, RV-S&FA, DISA)
Parth Shah who is head of Accounts and Book keeping has experience of more than 10 years. A Certified Public Accountant – US, fellow Chartered Accountant, Registered Valuer and Diploma in Information System Audit.