

The 8 Factors of Revenue Ruling 59-60: What Every Business Owner Must Know

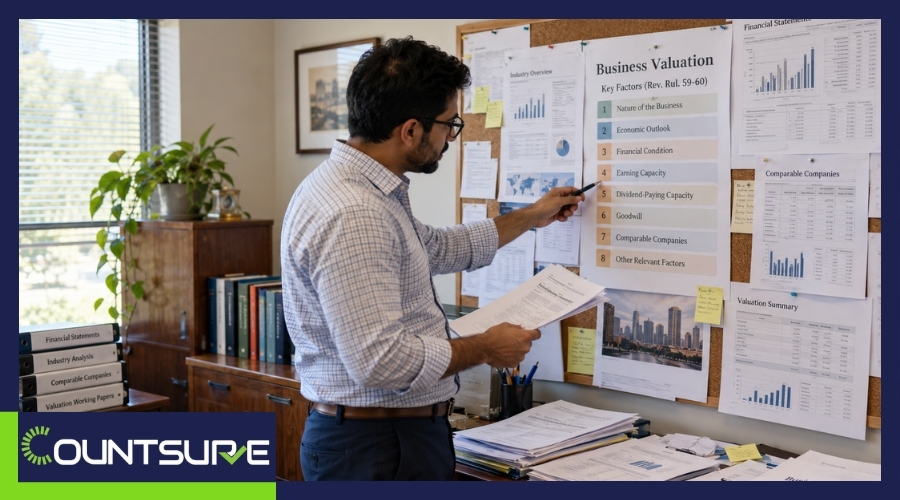
The short answer: Revenue Ruling 59-60 is the IRS guidance, issued in 1959, that sets out how to value stock in a closely held business at fair market value. It requires the appraiser to weigh eight factors: the nature and history of the business, the economic and industry outlook, book value and financial condition, earning capacity, dividend-paying capacity, goodwill and intangibles, prior stock sales and block size, and the prices of comparable public companies.
Understand how the IRS values your closely held business, and what it means for your estate, succession, or sale.
Key Takeaways
- Still the standard: Revenue Ruling 59-60 remains the core IRS framework for valuing closely held businesses, more than 65 years after it was issued.
- Eight factors, no formula: the appraiser must consider all eight factors and weigh them on the facts, not apply a fixed formula.
- Earning capacity usually leads: for most operating companies, normalized earnings carry the most weight.
- Block size matters: minority interests usually attract a discount for lack of control, and private stock a discount for lack of marketability.
- Wide reach: the ruling began with estate and gift tax, and its principles now guide income tax and 409A valuations too.
- Defensibility is the goal: an appraisal that addresses every factor is the strongest protection in an IRS review.
Why Revenue Ruling 59-60 Matters for Your Business
Issued in 1959, Revenue Ruling 59-60 remains the gold standard used by the IRS and courts to determine the fair market value of private, closely held businesses. Whether you are navigating estate planning, gifting equity, preparing for an M&A transaction, or facing an IRS audit, understanding this ruling is essential.
For business owners, shareholders, and successors, following this IRS-compliant valuation framework is the most effective way to ensure tax efficiency and prevent costly legal disputes.
How the ruling defines fair market value: the price at which property would change hands between a willing buyer and a willing seller when the buyer is not under any compulsion to buy and the seller is not under any compulsion to sell, both parties having reasonable knowledge of relevant facts. (IRS Revenue Ruling 59-60, Section 2.02)
The 8 Factors at a Glance
When valuing a business, the IRS requires a comprehensive analysis of the following non-exclusive factors.
Factor |
What the appraiser looks at |
Why it matters |
|---|---|---|
1. Nature and history
|
Formation, ownership, track record
|
A stable history lowers perceived risk
|
2. Economic and industry outlook
|
Macro trends, industry conditions, regulation
|
Growth sectors lift value; headwinds cut it
|
3. Book value and financial condition
|
Balance sheet, liquidity, financial health
|
Sets a baseline, rarely the final value
|
4. Earning capacity
|
Historical and expected profits, normalized
|
Usually the most important factor
|
5. Dividend-paying capacity
|
Ability to generate distributable cash
|
Measured whether or not dividends are paid
|
6. Goodwill and intangibles
|
Brand, technology, client relationships
|
Enterprise vs personal goodwill matters
|
7. Prior stock sales and block size
|
Arm's-length sales, size of interest valued
|
Drives minority discounts or control premiums
|
8. Comparable public company prices
|
Market multiples of similar public companies
|
Adjusted with a DLOM for private stock
|
Ready to simplify your valuation operations?
Let’s talk about how we can help your firm scale smarter.
The 8 Valuation Factors Explained
Each factor plays a distinct role in determining the defensible, audit-ready value of your closely held business.
1. Nature and History of the Business
This factor examines your company’s formation, ownership structure, and operational history. Establishing a stable, well-documented history reduces perceived risk. A business that has successfully navigated past economic downturns will generally command a stronger valuation.
2. Economic Outlook and Industry Conditions
Valuations do not happen in a vacuum. This factor evaluates how macroeconomic trends and industry-specific conditions impact your business. Regulatory headwinds may pull value downward; operating in a high-growth sector can boost your baseline.
3. Book Value and Financial Condition
While book value provides a baseline, it rarely represents fair market value, especially for service-based businesses. The IRS looks at your balance sheet to assess liquidity and financial health. Clean, audited financials are critical to maximizing this factor.
4. Earning Capacity
Often the most significant factor for operating companies, this looks at historical profit and future earning potential. For professional practices, normalizing owner compensation is critical: stripping away discretionary expenses to reveal true profitability.
5. Dividend-Paying Capacity
The IRS focuses on your business’s capacity to generate and distribute cash, regardless of whether you actually pay dividends. Strong free cash flow signals a more attractive investment to a hypothetical buyer and commands a higher valuation.
6. Goodwill and Intangible Assets
Intangibles like brand reputation, patented technology, and loyal client lists significantly impact value. A common question: is goodwill tied to the enterprise itself or to the owner’s personal reputation? This is a critical distinction in transition planning.
7. Prior Stock Sales and Block Size
Recent arm’s-length transactions involving your company’s stock provide concrete valuation evidence. The IRS also considers the size of the block being valued: minority interests typically warrant a discount, while controlling interests may carry a premium.
8. Market Price of Comparable Public Stocks
When available, appraisers analyze market data of comparable public companies. Because your private company lacks the liquidity of public stock, a Discount for Lack of Marketability (DLOM) is often applied to bridge the gap between public multiples and private realities.
Why These Factors Matter for Your Business
The eight factors shape real decisions, from tax filings to succession and sale.
Estate and Gift Tax
A defensible valuation ensures you do not overpay taxes on transferred wealth and protects you from IRS penalties. See our IRS-compliant gift and estate tax valuations.
Succession Planning
Understanding your value helps structure buy-sell agreements and smooths the transition to the next generation.
M&A and Buyouts
Objective valuations based on these 8 factors prevent shareholder disputes and set realistic expectations for a sale.
IRS Audit Defense
An appraisal rooted firmly in Rev. Rul. 59-60 is your strongest shield against aggressive IRS challenges.
Why These Factors Matter for Your Business
Avoid these pitfalls that can trigger audits, penalties, and shareholder disputes.
- Relying on rigid rules of thumb or simplistic revenue multiples to determine your business value.
- Failing to normalize financial statements to reflect true operational earnings and profitability.
- Ignoring the necessity of minority interest discounts (DLOC) and marketability discounts (DLOM).
- Attempting a DIY valuation instead of securing a defensible appraisal from a credentialed valuation professional.
Frequently Asked Questions
1. Is Rev. Rul. 59-60 still valid today?
Yes. Despite being issued in 1959, Revenue Ruling 59-60 remains the foundational authority relied upon by the IRS, courts, and valuation professionals to determine the fair market value of closely held businesses. Its eight-factor framework continues to shape every defensible appraisal.
2. How often should I get a valuation?
It is recommended to obtain a formal valuation whenever equity is issued, gifted, or transferred, or annually if you operate a stock option plan or have an active buy-sell agreement. Regular valuations keep your records defensible and your planning current.
3. What documents do I need to provide?
You will typically need 3 to 5 years of historical financial statements, tax returns, current year-to-date financials, projected financials, organizational documents (such as operating agreements), and details regarding any previous equity transactions or ownership changes.
4. How much does a business valuation cost?
Costs vary based on the complexity and size of the business, but investing in a certified, IRS-compliant appraisal pays for itself by mitigating audit risks and optimizing tax strategies. Contact us for a precise quote during your free consultation.
5. What are the 8 factors of Revenue Ruling 59-60?
The eight factors are: the nature and history of the business; the economic outlook and industry conditions; book value and financial condition; earning capacity; dividend-paying capacity; goodwill and other intangible value; prior sales of the stock and the size of the block being valued; and the market price of stocks of comparable public companies.
6. How does Revenue Ruling 59-60 define fair market value?
It defines fair market value as the price at which property would change hands between a willing buyer and a willing seller when neither is under any compulsion to buy or sell and both have reasonable knowledge of the relevant facts.
7. Does Revenue Ruling 59-60 apply only to estate and gift tax?
It was issued for estate and gift tax valuations, but Revenue Ruling 68-609 extended its approach to income tax matters. Its principles are now applied across most tax-related valuations of closely held businesses, including 409A valuations of private company stock.
8. Does Revenue Ruling 59-60 require a specific formula?
No. The ruling states that valuation is not an exact science and that no general formula applies to every case. The appraiser must weigh all eight factors using sound judgment, giving each factor the weight the facts of the business justify.
Protect your estate: get an IRS-compliant valuation today
Talk to a certified expert and get started in 24 hours. No obligation. 100% confidential.
Related Countsure Blogs
- 409A Valuation vs. Fair Market Value: Key Differences: how the IRS fair market value standard applies to private company stock and where a 409A appraisal differs.
- 409A Valuation Methods: A Founder’s Guide to Pre-OPM Value: how the market, income and asset approaches set enterprise value, the same approaches Rev. Rul. 59-60 asks appraisers to weigh.
- What Is a 409A Valuation? The Essential Guide to Avoiding Costly IRS Penalties in 2026: when private companies need an independent appraisal and what happens when stock is mispriced.

Parth Shah, Managing Director
(CPA-US, FCA, RV-S&FA, DISA)
Parth Shah who is head of Accounts and Book keeping has experience of more than 10 years. A Certified Public Accountant – US, fellow Chartered Accountant, Registered Valuer and Diploma in Information System Audit.
