

409A Valuation Methods: A Founder’s Guide to Pre-OPM Value

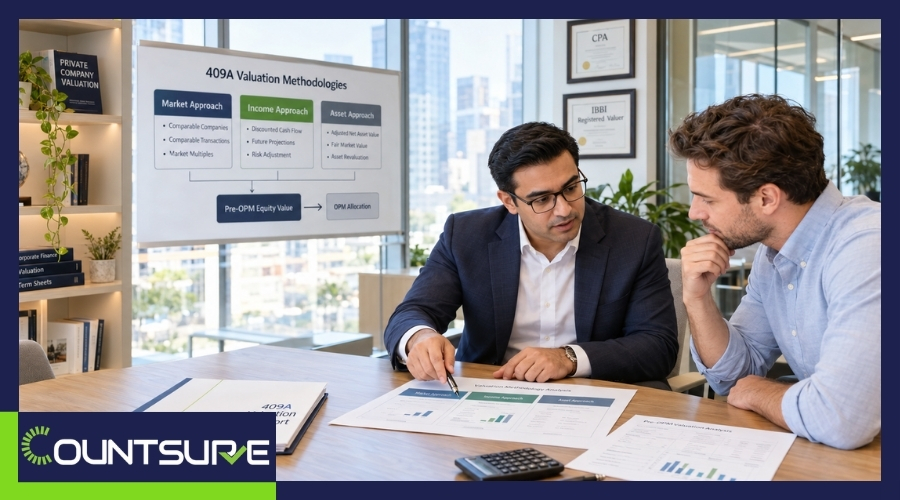
The short answer: A 409A valuation happens in two steps. First, the appraiser values the whole company using the market approach (comparable companies, transactions or a backsolve from your latest round), the income approach (discounted cash flow) or the asset approach (net assets), and converts that to equity value. Then the option pricing model (OPM), or a similar allocation method, splits that equity value across preferred and common stock, and a marketability discount is applied to reach the fair market value per common share.
A 409A valuation sets the fair market value of your common stock, which supports the strike price of your stock options and protects your team from IRS penalties. Before an appraiser can set a per-share price with the OPM, they first have to value the company as a whole.
- Market approach: compares your company with similar businesses and recent deals.
- Income approach: values your expected future cash flows.
- Asset approach: values what the company owns, less what it owes.
Understanding these methods will help you prepare for annual valuations and new funding rounds, and to read your valuation report with confidence.
Key takeaways
- Two steps: value the whole company, then allocate that value to each share class.
- Three approaches: market, income and asset; appraisers consider all three and weight them.
- Backsolve is common: after a priced round, the round price usually anchors the valuation.
- Enterprise to equity: subtract debt and add cash before allocating.
- Allocation: the OPM is most common; PWERM, hybrid and current value methods fit other situations.
- Marketability discount: common stock in a private company is worth less than a freely traded share.
Defining the Baseline: What Are 409A Valuation Methods?
The goal of a 409A valuation is to find the fair market value of a private company’s common stock, so that options are granted at or above that value. An independent appraisal that meets the conditions gives the company safe harbor protection under Section 409A.
Before setting a per-share value for common stock, the appraiser must value the business as a whole. You cannot allocate value across a cap table without first knowing what the company is worth.
The 409A regulations say a reasonable valuation must consider factors such as the value of the company’s assets, its expected future cash flows, and the values of comparable companies. Revenue Ruling 59-60 sets out similar factors. Appraisers address them through three approaches:
| Approach | Main methods | Best suited to |
|---|---|---|
| Market approach | Guideline public company, guideline transaction, and backsolve from a recent financing | Companies with a recent priced round or good comparables; the most common approach for venture-backed startups |
| Income approach | Discounted cash flow (DCF) | Companies with revenue and projections reliable enough to forecast, usually later stage |
| Asset approach | Adjusted net asset method | Very early companies with no priced round and little revenue, and holding companies |
The right weighting depends on the company’s stage, from seed to Series C and beyond, its industry, and how reliable its financial data and forecasts are.
The Market Approach: Benchmarking Against Peers and Deals
The market approach values a company by reference to what investors have paid for similar businesses. It rests on the principle of substitution: an informed buyer would not pay more for a business than the price of a comparable one.
Guideline Public Company Method (GPCM)
Compares your company with publicly traded companies, using multiples such as enterprise value to revenue or to EBITDA, and adjusts for differences in size, growth, margins and risk.
Guideline Transaction Method (GTM)
Uses the multiples paid in acquisitions of comparable companies to set an appropriate multiple for yours.
Backsolve From a Recent Financing
For venture-backed companies, the most important market evidence is usually your own latest round. In a backsolve, the appraiser finds the total equity value at which the OPM gives the new preferred shares exactly the price investors paid. This is not the headline post-money valuation, which assumes every share, including common, is worth the preferred price.
Worked example (hypothetical): a SaaS startup has $4,000,000 of annual recurring revenue. Comparable public SaaS companies trade at about 6.0x revenue; adjusted down for the startup’s smaller size and higher risk, the appraiser applies 5.0x.
| Step | Amount |
|---|---|
| Annual recurring revenue | $4,000,000 |
| Risk-adjusted EV/revenue multiple (peers at 6.0x, adjusted down for size and growth) | 5.0x |
| Enterprise value | $20,000,000 |
| Less: debt | ($1,000,000) |
| Add: cash | $3,000,000 |
| Equity value to allocate | $22,000,000 |
Because it relies on observable market data, a well-supported market approach carries weight with auditors and the IRS.
The Income Approach: Projecting Future Cash Flows
The income approach values a company from the cash flows it is expected to generate, discounted to present value. The usual method is the discounted cash flow (DCF).
The appraiser projects cash flows, typically for five to ten years, and discounts them at a rate that reflects the risk of achieving the plan: a weighted average cost of capital for more mature companies, or a venture capital rate of return for earlier ones. A terminal value captures the years beyond the forecast.
The income approach suits revenue-generating companies, often Series B and later or pre-IPO, with forecasts reliable enough to model. Doing it well requires careful work on capital spending, working capital and growth assumptions, and on whether management’s projections are achievable.
The Asset Approach: Valuing the Balance Sheet
The asset approach, usually the adjusted net asset method, values a company at the fair market value of its assets less its liabilities.
It is generally used for very early companies that have not raised a priced round and have little revenue, where value is largely the cash raised (for example from SAFEs or convertible notes) and early intellectual property. It also suits holding companies and businesses facing liquidation.
Once a company is generating recurring revenue or has raised a priced round, the asset approach rarely captures its value, because most of that value is intangible: the team, the product and the growth ahead.
Want to talk through your projections?
Book a free 30-minute consultation with Countsure to discuss which approach fits your company.
Bridging the Gap: From Company Value to Per-Share Value
Once the appraiser has a value for the whole company, they convert enterprise value to equity value by subtracting debt and adding cash. That equity value is the main input to the allocation step.
The Option Pricing Model (OPM)
The OPM treats each class of equity as a call option on the company’s equity value. Breakpoints are set at each liquidation preference and conversion point, so preferred stock, which is paid first, receives more of the value at low outcomes, and common stock shares in the upside above the preferences. The model needs inputs for expected time to exit, volatility (usually from public peers) and the risk-free rate.
Other Allocation Methods
| Method | How it works | When it is used |
|---|---|---|
| Option pricing model (OPM) | Treats each share class as a call option on the company's equity value, with breakpoints at each liquidation preference | Most venture-backed companies where an exit is not near |
| Probability-weighted expected return method (PWERM) | Values specific exit scenarios (sale, IPO, dissolution) and weights them by probability | Companies with a reasonably foreseeable exit |
| Hybrid method | Combines PWERM scenarios with an OPM for the uncertain scenario | Later-stage companies with one likely exit path |
| Current value method (CVM) | Assumes an immediate sale and pays out by the liquidation waterfall | Very early companies, or when a sale is imminent |
The Marketability Discount
Common stock in a private company cannot be sold easily, so the allocated value is reduced by a discount for lack of marketability (DLOM), usually estimated with option-based models or restricted stock studies.
Worked example (continued, illustrative):
| Step | Amount |
|---|---|
| Equity value | $22,000,000 |
| Value allocated to common stock by the OPM (illustrative) | $7,600,000 |
| Fully diluted common shares and options | 9,500,000 |
| Common value per share before discount | $0.80 |
| Discount for lack of marketability (30%, illustrative) | ($0.24) |
| Fair market value per common share | $0.56 |
Why the Method Matters
The accuracy of the OPM allocation depends on the quality of the company value that goes into it. Whether the appraiser leans on the market, income or asset approach, that value has to be well supported.
- Tax risk for employees: options priced below fair market value can bring tax, a 20% additional federal tax and interest for the holders.
- Delays in deals: a weak valuation can be questioned in fundraising or acquisition due diligence.
- Trust: investors and employees lose confidence when equity pricing has to be revisited.
For the full rules and penalties, see our 409A valuation guide.
Why Choose Countsure?
- Expert-led analysis: valuations led by a US CPA and Registered Valuer.
- Transparent pricing: fixed fees, typically from $1,500 to $15,000 depending on complexity, confirmed before we start.
- Clear timelines: reports usually delivered in 9 to 12 days once we have your data. See our 409A valuation timeline.
Ready to Get a Well-Supported 409A Valuation?
Schedule a free consultation with Countsure’s valuation team. We will discuss your company, answer your questions and give you a fixed quote, with no obligation.
Frequently Asked Questions
1. What are the primary 409A valuation methods?
Appraisers use three approaches to value the company as a whole: the market approach, the income approach and the asset approach. They usually consider all three and weight them depending on the company’s stage, data and recent financings. That total value is then allocated to the share classes, usually with an option pricing model, to find the value of common stock.
2. How does the market approach work for 409A valuations?
It compares your company with similar public companies or acquisitions, using multiples such as enterprise value to revenue or to EBITDA, adjusted for differences in size, growth and risk. For venture-backed companies, the most common market method is the backsolve, which works back from the price investors paid in your latest round.
3. What is the income approach in a 409A valuation?
The income approach values a company from its expected future cash flows. The usual method is discounted cash flow (DCF): cash flows are projected for five to ten years and discounted to present value at a rate that reflects the risk of hitting the plan.
4. When is the asset approach used?
The asset approach values a company at the fair market value of its assets less its liabilities. It suits very early companies with no priced round and little revenue, holding companies, and businesses facing liquidation. It rarely captures the value of a growing company’s intellectual property and team.
5. What is the option pricing model (OPM) and why is it important?
The OPM allocates the company’s total equity value among its share classes. It treats each class as a call option on the equity value, with breakpoints at each liquidation preference, so it can price common stock below preferred stock in a way that reflects their different rights. A discount for lack of marketability is then usually applied to the common value.
6. Which valuation method is best for my startup?
It depends on your stage, industry and data. A company with a recent arm’s-length priced round usually relies on a backsolve; a pre-revenue company with no round may lean on the asset approach; a later-stage company with reliable forecasts may weight the income approach. A thorough valuation considers all three and explains the weighting.
7. How does a recent funding round affect the valuation?
A recent arm’s-length round is strong evidence of value. In a backsolve, the appraiser solves for the total equity value at which the OPM gives the new preferred shares exactly the price investors paid. That is different from the headline post-money valuation, which assumes every share is worth the preferred price.
8. Are these methods approved by the IRS?
The IRS does not approve specific methods. The 409A regulations list factors a reasonable valuation must consider, such as asset values, expected cash flows and the values of comparable companies, and Revenue Ruling 59-60 sets out similar factors. The market, income and asset approaches are the standard ways appraisers address them.
Related Countsure Blogs
- 409A Valuation Guide: costs, penalties and safe harbor explained.
- 409A Safe Harbor Guide: what gives a valuation its presumption of reasonableness.
- When Is a 409A Valuation Required?: the events that trigger a refresh.
- Sample 409A Valuation Report: what the finished report looks like.

Parth Shah, Managing Director
(CPA-US, FCA, RV-S&FA, DISA)
Parth Shah who is head of Accounts and Book keeping has experience of more than 10 years. A Certified Public Accountant – US, fellow Chartered Accountant, Registered Valuer and Diploma in Information System Audit.
